
AI in FSI: The Black Box Is Ready, the Bureaucracy Is Not
- By Winston Thomas
- November 10, 2025
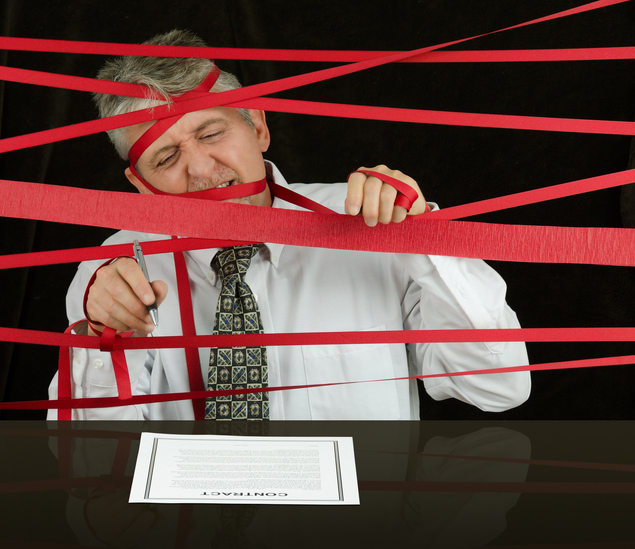
AI engineers at Asian banks are at a loss: On one hand, they have a lightning-fast, hyper-efficient AI co-pilot ready to automate risk assessment, obliterate fraud, and personalize customer journeys with predictive power. On the other hand, they are shackled by reality, knowing their brilliantly optimized, high-performing models will spend the next nine months waiting for a Model Risk Management (MRM) Committee sign-off.
Ask any AI engineer or developer, and get past the veneer of positivity, and you’ll reach the unspoken consensus: compliance is the true AI latency.
This is not about AI offering alpha in the banking sector. It does, offering hundreds of billions in potential value, primarily through efficiency and revenue generation, according to a World Economic Forum report.
The real question is whether the rapidly evolving, risk-averse regulatory superstructure is inherently holding back the speed and ambition of AI engineering. And the answer, framed by the banking world’s mandate for stability, is complicated: Regulation acts as a friction point, but it’s a necessary friction that ultimately forces the industry to build better, safer systems.
Where engineering meets friction
For an AI engineer, the path from sandbox to production is littered with what seem like arbitrary roadblocks.
The single largest technical conflict is the explainability mandate. Modern deep learning models, which excel at identifying novel fraud patterns or processing vast amounts of unstructured text in loan documents, are often referred to as “black boxes.” They generate incredible results, but their internal logic is impossible to trace in terms that are human-understandable.
This lack of transparency can rub compliance the wrong way. If a model denies a customer a loan, the customer (and more importantly, the regulator) has a right to a clear explanation of why. If the engineer cannot provide that narrative, the model is dead on arrival. This forces a trade-off: engineers must often abandon the highest-performing, most opaque models in favor of less powerful but more interpretable algorithms, sacrificing computational gains at the altar of auditing.
Furthermore, the focus on algorithmic bias is a massive engineering overhead. Banks are not just worried about data breaches; they are also concerned about the social instability that can occur when one happens. If an AI model, trained on historical lending data reflecting past societal inequalities, perpetuates discrimination, it exposes the bank to lawsuits and regulatory enforcement. This requires engineers to invest considerable resources in debiasing techniques, fairness audits, and continuous monitoring to ensure the model doesn’t drift toward discriminatory outcomes based on demographics. It’s not just code; it’s social engineering.
And then there’s MLOps, the practice of deploying and maintaining machine learning models. In banking, MLOps is complicated by legacy systems [Source 1.4] and the need for human-in-the-loop (HITL) processes. Every model deployment involves integrating cutting-edge API services with decades-old, core banking infrastructure, and then building an audit mechanism to ensure a human can always override a decision. This multiplies complexity and development time exponentially.
The systemic trade-off: Guardrails over gains
While it is easy for the AI engineer to curse the slow-moving compliance department, the financial sector has a responsibility that other tech industries do not: systemic stability.
Regulators are primarily concerned with preventing an AI-induced systemic shock. The widespread use of common AI models and data sources could lead to market correlation, where a single model failure, error, or adversarial attack propagates instantly across the entire financial system, exacerbating crises. This is why the regulatory push from the Monetary Authority of Singapore, the Hong Kong Monetary Authority, and the Federal Reserve, as well as the European Union’s AI Act, is focused less on innovation and more on risk-proportionate governance.
In this light, the perceived friction is actually a necessary guardrail. The existing regulatory frameworks, even if they seem cumbersome when applied to GenAI, compel banks to prioritize data governance, accountability, and security over profits. They ensure that AI is a tool for risk reduction (fraud detection, compliance automation) rather than just a reckless accelerator for revenue generation.
The slow pace ensures the AI is resilient against manipulation (data poisoning) and that the bank has clear accountability for every automated decision. Without that, public trust, which is a bank’s true currency, would evaporate overnight.
X marks AI’s future in banking
The conflict between speed and safety is solvable, and the resolution lies squarely in the engineer’s hands: Explainable AI (XAI).
XAI is not just a regulatory hurdle; it is the compliance primitive that will define the next generation of financial technology. It represents the technical bridge between a high-performing model and regulatory necessity.
Future AI engineers won’t just build faster models; they will create models that are natively interpretable. They will use techniques that allow them to demonstrate, with technical certainty, that the AI is fair, auditable, and non-biased, all while maintaining the high performance that modern finance demands. The banks that succeed won’t be the first to adopt every shiny new AI tool; they will be the ones whose engineers can reliably transform a powerful black box into a transparent, auditable decision engine.
In this light, the future of AI in banking isn’t held back by regulation; it’s being fundamentally shaped and strengthened by it. And it matters when the customer base, both at the retail and private institution side, shifts to machines.
Image credit: iStockphoto/mokee81


Winston Thomas
Winston Thomas is the editor-in-chief of CDOTrends. He likes to piece together the weird and wondering tech puzzle for readers and identify groundbreaking business models led by tech while waiting for the singularity.